Your Path to Homeownership
Starts Here
Even if traditional financing isn't the right fit.
Buying a home doesn't always have to follow the traditional path. Whether you're working on your credit, need more time to qualify for a mortgage, or simply want to explore purchasing a home with no down payment, Houzable can help you explore your options.
We offer access to two alternative paths to homeownership: Lease-to-Own and Zero Down Financing.
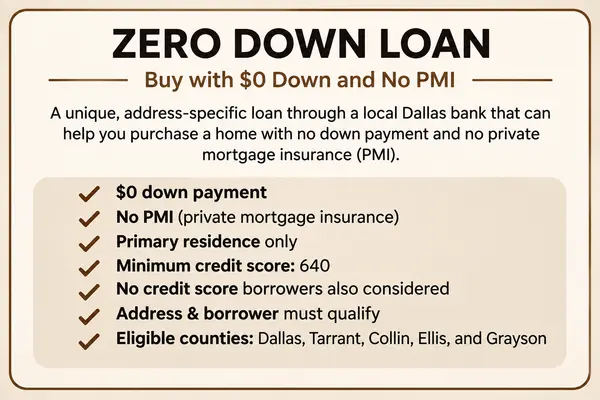
Option 2: Zero Down Mortgage
Yes, buying a home with $0 down may be possible.
What if you could purchase a home without saving tens of thousands of dollars for a down payment?
Through a local Dallas-area bank, eligible buyers may qualify for a mortgage requiring zero down payment and no private mortgage insurance (PMI).
That means you may be able to purchase a home sooner while keeping more of your savings available for other expenses.
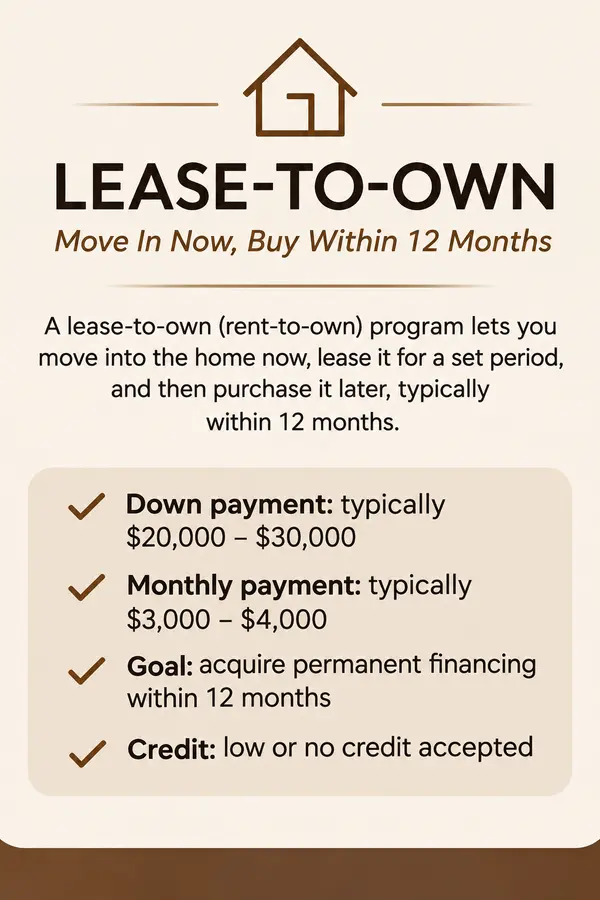
Option 1: Lease-to-Own
Move in now. Work toward buying within 12 months.
Love the idea of owning a home but aren't quite ready for a traditional mortgage?
Our Lease-to-Own option allows you to move into a home today while working toward securing permanent financing, generally within 12 months.
This can be an excellent option for buyers who have the funds to move forward but need additional time to establish credit, improve their financial profile, or qualify for a mortgage.
Lease-to-Own FAQs
To help you make informed decisions, we've compiled answers to some of the most commonly asked questions.
Sellers determine the down payment; commonly ranging between $20,000 - $30,000.
Do I actually own the home I'm leasing-to-buy?
Who pays for repairs and maintenance?
How does my credit score affect my lease-to-own eligibility?
How Does It Work?
Who Is This Best For?
Important: Terms vary by property and agreement. Upfront payments, purchase options, payment credits, and refundability should be reviewed before signing. Financing and eventual purchase are not guaranteed.
Zero Down Loan FAQs
To help you make informed decisions, we've compiled answers to some of the most commonly asked questions.
Typically you need 3% - 20% down, but with this address specific and borrower qualification required loan, you could have a zero down payment.
What homes qualify for the zero down loan?
Who Is This Best For?
Important: Zero down does not necessarily mean zero closing costs or zero cash needed at closing. Loan approval, property eligibility, lender underwriting, and program availability apply.